For generations, stokvels have played an important role in South Africa’s financial culture, bringing people together through a shared commitment to saving, supporting one another and building financial security. Whether saving towards groceries, festive-season expenses, school fees or household needs, these collective savings groups have remained an important part of how many South Africans manage their money.
However, the traditional stokvel model is beginning to evolve. Beyond the familiar December and January payouts, more groups are exploring opportunities to invest, purchase property, support entrepreneurship and build wealth that extends beyond immediate financial needs.
With the festive-season payout period approaching, the conversation around stokvels is becoming increasingly relevant. While many members are preparing to access their hard-earned savings, it also presents an opportunity for groups to reflect on their financial goals, strengthen governance, protect their contributions against fraud and consider whether a portion of their savings could be put towards longer-term financial growth.
In this interview, Absa’s Lead for Group Savings Product Management ,Palesa Lengolo unpacks how South Africa’s stokvel landscape is changing, what groups should consider before the upcoming payout season and how collective savings can create opportunities for sustainable wealth creation.
From deciding whether to withdraw or reinvest year-end savings to understanding financial controls, digital banking security and the future of investment-focused stokvels, the conversation offers practical insights for groups looking to make more informed financial decisions as they prepare for 2027.
01. The evolution of stokvels
Stokvels have traditionally been associated with saving money throughout the year and sharing the proceeds during the festive season. Today, we’re seeing more conversations around investing, property ownership and entrepreneurship. What is driving this shift, and how are stokvels evolving beyond their traditional purpose?
Stokvels have always been about collective financial resilience, but their purpose is evolving significantly. While many groups still save for groceries, school expenses and festive-season spending and that’s nothing new a growing number are now focusing on wealth creation through property, entrepreneurship and investments.
At Absa our book demonstrates this trend very clearly – in the last three years we have seen significant growth in the number of investment clubs. We have also seen the rate of growth in investment clubs outperform the growth in more traditional grocery and travel savings clubs by a great margin.
Several factors are driving this shift. Firstly, South Africans are increasingly aware that savings alone may not be enough to keep pace with inflation and rising living costs. Secondly, greater access to financial education and digital banking tools is making it easier for stokvels to explore investment opportunities. Thirdly, younger and more professionally diverse members are joining stokvels and bringing new aspirations around asset ownership and long-term wealth accumulation.
The sheer scale of the sector also creates new opportunities. According to the National Stokvel Association of South Africa (NASASA), there are more than 800,000 stokvels with over 11 million members, collectively contributing around R50 billion annually.
What is particularly encouraging is that many stokvels are becoming increasingly aware of their collective economic power and are longer viewing themselves purely as savings clubs.
We believe we will continue seeing a rise in investment collectives purchasing property, funding small businesses, generating rental income and building assets that can benefit members for years to come.
02. The role of the Absa Stokvel Awards
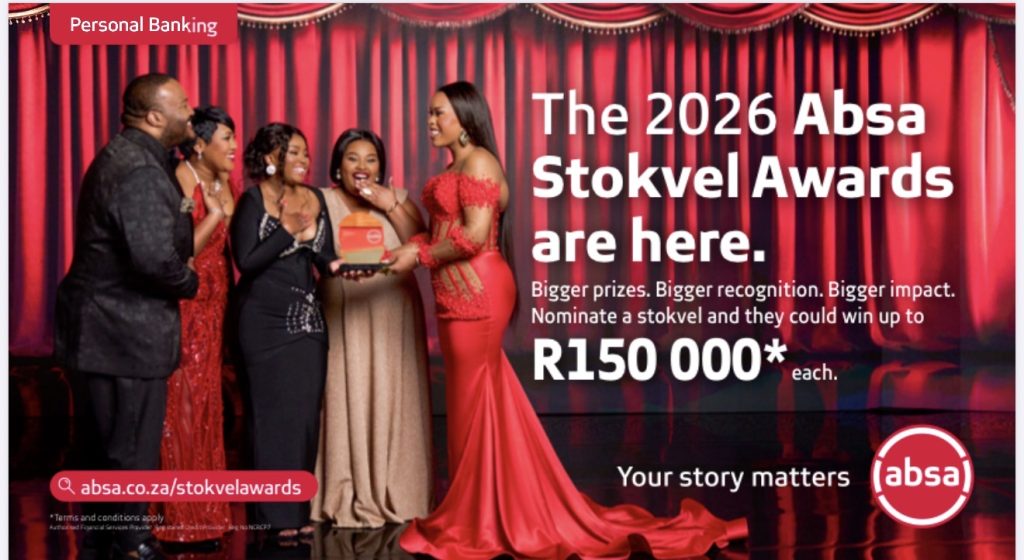
Now in its third year, the Absa Stokvel Awards celebrates groups that are using collective saving and collaboration to build wealth and strengthen their communities. What inspired the Awards, and what have you observed about the stokvels that are making a meaningful difference in their communities?
The Absa Stokvel Awards were established to recognise and celebrate the extraordinary role stokvels play in promoting financial inclusion, disciplined saving and community development across South Africa. The awards acknowledge that stokvels are far more than savings mechanisms. They are vehicles for empowerment, entrepreneurship and social impact.
Over the years, we’ve seen stokvels use collective resources to support education initiatives, create employment opportunities, fund community upliftment projects and assist vulnerable households. Many of the standout entrants demonstrate strong governance, financial discipline and a commitment to improving the lives of others beyond their own membership base.
A common characteristic among the most impactful stokvels is that they combine sound financial management with a clear purpose. They understand that when people save and invest together, they can achieve outcomes that may be difficult to accomplish individually.
Nominations for the Awards closes at the end of October and are excited to see how the sector has developed through our this year’s nominees.
03. Preparing for the December 2026 and January 2027 payout season
With the festive season approaching, many stokvel members are preparing to receive their payouts. What practical steps should stokvels be taking now to ensure their funds are secure, their records are in order and members have agreed on how the money will be distributed or used?
The weeks leading up to payout season are some of the most important in the stokvel calendar. Good preparation on the part of members will reduce the risk of disputes and strengthens trust among members in the long term.
Stokvels should prioritise:
• Reconciling all member contributions and ensuring records are accurate and up to date.
• Conducting a final review of bank balances and supporting documentation.
• Confirming payout calculations and ensuring membersunderstand how distributions will be made.
• Verifying signatories and banking details before any payments are processed.
• Holding a formal meeting to agree on the timing, purpose and distribution of funds.
• Avoiding large cash withdrawals where possible and using electronic transfers instead.
• Maintaining clear written records of all decisions and payouts.
Among these, I would like to underscore the importance of putting safety first by reducing the reliance on cash. Where possible, stokvels should pay members electronically rather than withdrawing large sums of cash. Absa stokvel customers can register for online banking and make EFT payments directly to members, while also accessing electronic statements and tracking contributions online.
04. Should stokvels withdraw or reinvest?
For many members, the year-end payout is something they look forward to all year. However, could withdrawing the entire savings pot every December limit a stokvel’s potential to build long-term wealth? What alternatives could groups consider while still meeting members’ immediate financial needs?
Many stokvels have a clearly defined purpose and savings goal, aligned with the financial needs of the members. For many, a full year-end payout meets the need that inspired the savings behaviour. This traditional stokvel model remains relevant as it often serves an important purposesuch as helping members fund festive-season expenses, school costs and household needs.
Groups could consider paying out what members need and leaving a portion of their savings in the account to continue earning interest and building towards future goals.
For example, the Absa Investment Club currently offers competitive interest rates of up to 6.80% p.a., while providing immediate access to funds. This means a stokvel can keep some money invested and earning interest rather than starting from zero again after every annual payout.
Ultimately, the right approach depends on the stokvel’s purpose and what members agree will best meet their short- and longer-term financial needs.
This approach allows members to benefit from their savings today while creating opportunities for greater long-term growth and wealth creation.
One approach is not necessarily better than another, but it all boils down to what kind of financial support the stokvel members require and opt for.
Many stokvels save for a specific purpose, so paying out members at year-end may be exactly what the group needs. However, stokvels do not always have to withdraw the full amount.
05. Protecting members against fraud and financial crime
Payout season can create opportunities for fraudsters targeting large amounts of pooled savings. What are the most common risks stokvels should be aware of, and what security measures, including secure digital banking practices, can groups put in place to protect their collective money?
Payout season unfortunately attracts criminals because stokvels often handle larger sums of money during this period. Common risks include phishing scams and fake banking communications, cash theft during withdrawalsand even fraudulent investment schemes promising unrealistic returns.
We advise stokvels to:
• Use reputable financial institutions and formal stokvel banking accounts.
• Enable banking alerts and transaction notifications.
• Require dual or multiple approvals for payments.
• Verify beneficiary details independently before making transfers.
• Avoid sharing passwords, PINs or one-time passwords (OTPs).
• Limit cash handling and use electronic payments wherever possible.
The safest money is money that remains within secure, regulated banking channels.
06. Governance, trust and accountability
Because stokvels depend on trust between members, financial mismanagement or disagreements can threaten the group’s survival. What financial controls should every stokvel have in place, from transparent record-keeping and regular reporting to managing signatories and approving withdrawals?
Trust is the foundation of every successful stokvel, but trust works best when supported by clear governance.
Every stokvel should have:
• A written constitution.
• Clearly defined roles and responsibilities.
• Transparent financial records.
• Regular member reporting.
• Multiple authorised signatories. For example, when registered for internet banking app at Absa as a group – one initiates a payment and the other signatories authorise.
• Formal approval processes for withdrawals and investments.
• Regular meetings with documented minutes.
• Annual reviews of rules and governance arrangements.
Strong governance not only protects members’ funds but also position stokvels to access broader financial services and investment opportunities as they grow.
07. Moving from saving to investment and wealth creation
For stokvels interested in moving into property ownership, entrepreneurship or other investment opportunities, what should they understand before taking that next step? How can groups assess their financial readiness, manage risk and make informed decisions without putting members’ hard-earned contributions in jeopardy?
As suggested before, before entering any investment trajectory, stokvel members need to agree that the new direction of travel continues to meet the financial goals of members and their risk appetite.
Additionally, stokvels need to ensure they have the appropriate foundation in place. Depending on the savings or investment goal, this may include having sufficient capital beyond short-term obligations, having members within the group who have a level of investment expertise, clear governance around how decisions will be made and monitored. And importantly, an agreement around what happens when things don’t go as planned.
Where members lack the requisite knowledge or experience, it is important to do research or seek professional advice.
08. The future of stokvels in South Africa
Looking towards 2027 and beyond, what trends do you believe will shape the future of stokvels? How can financial institutions such as Absa support groups as they move from collective saving towards more sustainable wealth creation, financial inclusion and community development?
Looking ahead to 2027 and beyond, several trends are likely to shape the future of stokvels. Many of these I have already discussed such as growth in investment-focused stokvels and increased interest in property ownership and entrepreneurship. Furthermore, we expect to see increased digital adoption by stokvels, greater participation among youth and expanded financial education and advice services.
Research increasingly recognises stokvels as important contributors to financial inclusion, economic participation and community resilience. Nurturing these ideals is precisely why the Absa Stokvel Awards exist. Through this platform we celebrate and drive awareness of the opportunities and successes of collective savings.
Accessible financial education, appropriate guidance and secure digital tools are increasingly important. This is another area in which financial institutions can provide support.
The future of stokvels is likely to be defined by a blend of traditional community values and modern financial toolsand trends. Their enduring strength lies in their ability to bring people together around a common purpose, while increasingly generating pathways to broader economic participation and wealth creation.
